- Trusted Independent Agency Since 2011
Homeowners Insurance in Greater Lafayette
Homeowners Insurance - Lafayette Insurance
Get Home Insurance from Lafayette Insurance today!
Home insurance protects more than just your dwelling; it provides coverage for your belongings as well as liability. Most importantly, we will educate you on the covered perils and how to protect against them. Lafayette Insurance will find you money-saving discounts while adequately protecting your largest investment.
765-474-2300
Initial Consultation
Outside Inspection
Choose Options
Start Coverage
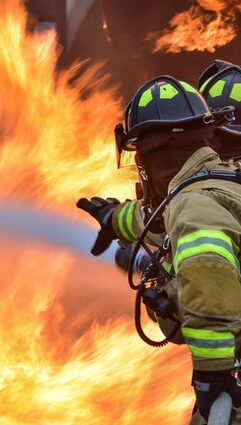
Covered Perils
Some Perils We Provide Coverage For.
A typical home insurance policy provides coverage for the perils listed below and more; however, we can add the additional coverages needed for other perils such as earthquake or sewer and drain.
Fire and Smoke
Lightning Strikes
Windstorm and Hail
Explosion
Vandalism and Mischief
Weight of Ice or Snow
Theft
Falling Objects
You can Depend on us to Get the Right Home Insurance Policy.
In other words, Lafayette Insurance is dedicated to providing the best homeowners insurance policies available to its clients at the most reasonable rates.
Home Insurance in Lafayette, West Lafayette and Tippecanoe County
From historic homes in Lafayette’s Ninth Street Hill and Perrin neighborhoods to newer subdivisions, West Lafayette homes near Purdue and country properties across Tippecanoe County, every home is different. Lafayette Insurance compares home insurance from multiple companies, including ERIE, Nationwide, Progressive Home, Foremost Signature, Openly and Universal Property, so your policy fits your home and your budget.
Local risks we plan for
Wind and hail. Spring and summer storms are a fact of life in Indiana. Check whether your roof is covered at replacement cost or actual cash value. On an older roof, the difference after a hail claim can be thousands of dollars. Read more in ACV vs. replacement cost roof coverage.
Water backup. A failed sump pump or a sewer backup isn’t covered by a standard policy unless you add water backup coverage. It’s one of the most valuable add-ons for homes with finished basements.
Flooding. Homeowners policies don’t cover flood. If you live near the Wabash River or a creek, ask about separate flood insurance.
Older homes. Plaster walls, original woodwork and older wiring can cost more to rebuild. We help set a dwelling limit that reflects real rebuilding costs, not just market value.
What affects your home insurance rate
Your home’s age, roof age and material, construction type, square footage, distance to a fire station and hydrant, claims history, deductible and credit-based insurance score all play a part. Each insurance company weighs these differently. That’s why comparing several companies through one independent agent often saves money.
Ways to save
- Bundle home with auto, umbrella or life
- Choose a higher deductible you’re comfortable with
- Ask about credits for a newer roof, security systems and updated plumbing or electrical
- Review your policy every year, especially after a remodel or a big purchase
Own a rental? See landlord insurance. Renting? See renters insurance. Living in a condo? See condo insurance.
What sets our home insurance companies apart
Companies we represent for home insurance include ERIE, Nationwide, Progressive Home, Openly, Universal Property and Foremost. Each one has its own strengths, and these are some of the options available through them:
- Better roof after a claim: If a covered claim requires a full roof replacement, some policies pay to install a stronger, more leak-resistant, longer-lasting roof.
- Full rebuild cost: Some policies pay the full cost to repair or rebuild your home without depreciation, even if it exceeds your policy limit.
- Water and flood protection: Flood and sewer or drain backup coverage can be added directly to some home policies.
- Jewelry without appraisals: Jewelry can be covered on a blanket basis, with no appraisals required.
- Identity theft and cyber protection: Coverage is available for identity theft expenses, credit card fraud, cyber extortion, cyberbullying and data recovery after a hack.
- Home systems breakdown: Optional coverage can pay for breakdowns of built-in equipment like a dishwasher or water heater.
Want to know what drives your price? Read what affects home insurance rates in Indiana.
Features, limits and availability vary by company and policy. Ask us which options fit you.
We've got answers
Frequently Asked Questions
1.What perils are excluded from home insurance policies?
Earthquake, flood, sewer drain, terrorism, and deterioration to name a few. Some of the perils are available by endorsement if you would like to add them.
2.What if my neighbor's tree fell on my fence?
Typically, your own policy would pay for this loss unless the falling tree was due to your neighbor's negligence.
3.Is my business insured by my homeowners policy?
Home insurance is not designed to protect business operations at your home. Some companies offer incidental business enhancement endorsements that provide some coverage while at home.
4.What home insurance discounts do I qualify for?
Age of home, age of roof, multiple policies, life discount, and more. We will search for all applicable discounts when preparing your quotes.
5.Why is replacement cost different than purchase price?
Replacement cost based on today's market is what it would cost us to duplicate your house if you had a total loss. It does not always correspond with purchase price.
6.What is loss of use coverage?
Loss of use provides you with temporary housing expenses during covered repairs.
7.Do I need liability coverage?
Liability coverage helps protect your assets and cover legal fees up to the liability limit on your policy when you are found legally liable for causing injury to other people or property. We always include liability with every home policy.
8.Does home insurance cover my stuff?
Personal property is the part of the home insurance policy that covers your belongings, subject to deductible.
9.What deductible should I choose?
We recommend choosing a deductible amount that you can afford should you need to use it. The higher the deductible, the lower the premium will be.
10.How much does home insurance cost?
Home insurance rates are determined by several factors, insurance score and age of property are two of the primary components. We would love an opportunity to provide you with an accurate quote today!
Lafayette Insurance Reviews
What our Clients Say
Stacey Minier
Joe and his staff are top notch. I never worry if I have an issue involving insurance. They are there to help make the experience worry free and professional. It’s worth your time to give Lafayette Insurance a call.
Daniel Layman
Tremendous support from Joe Couch. He was readily-accessible, diligent, and a tremendous help through the process of switching policies. Would recommend to everyone.
Jon Chapin
Joe Sr. and Jr. are both professional and do the very best they can to get you the best deal possible. They have reached out to me to let me know of opportunities to decrease my rates before my terms were up so I could plan accordingly. They always answer when I text or call with a problem. Can't say enough good things about this company or the people running it!
Devon Moore
Very professional and responsive. After calling several agencies in the area, our quote was 15% lower than anywhere else!
Isaac Schumacher
Joe Jr. looks out for you. Initially he had me with one insurance agency. 1 year in and upon finding a new deal, he contacted me, helped me save some money, and found a more reliant insurance company for my family's vehicles. He is personable and offers good advice without trying to overexert influence. I have not had to deal with a wreck yet and working through a claim, but I will update this post if it happens.
Jordan Hockema
Jasen Shaver
They are very nice and will find the best deal for you. They also follow up with you in the future to better you in better insurance for less.
Christoper Crable
The Couch team is great, I wound up switching to them from another company. I saved money, got better BOP coverage, better Work Comp coverage, and fadter service. I highly recommend them to any Business in the Lafayette area.
Licensed advisors that care about our clients
Our average client review is 4.9 of 5 Stars
We represent some of the top insurance companies
Affordable rates and quality service
Homeowners Insurance in Lafayette, West Lafayette and Zionsville
Whether you own a starter home near Purdue, a family home in Lafayette or a newer build in Zionsville, the right homeowners policy starts with the right dwelling limit. Make sure your coverage reflects what it would cost to rebuild your home today, which is often different from what you paid for it.
For higher-value homes, we also review your liability limits and whether a personal umbrella policy makes sense. Bundling your home with your auto insurance usually lowers the price of both. Renting instead? See renters insurance. Own rental property? See landlord insurance.
We insure homes in Lafayette, West Lafayette, rural Tippecanoe County and Zionsville.
Get a homeowners insurance quote: call or text 765-474-2300 or request a quote online.